Getting your first job is a major achievement. After completing interviews, documentation and joining formalities, receiving your first salary can feel like the most rewarding part of the journey.
But when you open your first salary slip, you may notice several unfamiliar terms: Basic Salary, HRA, Gross Salary, PF, ESI, Professional Tax and Net Pay.
You may also wonder why the amount credited to your bank account is lower than the salary mentioned in your offer letter.
Let’s understand it step by step.
What Is a Salary Slip?
A salary slip, also called a payslip, is an official document provided by an employer that explains an employee’s salary for a particular pay period, usually one month.
It generally includes:
- Employee name and identification details.
- Employer and department information.
- Salary components and allowances.
- Total earnings.
- Statutory and other deductions.
- Net salary payable.
A salary slip is useful beyond checking your monthly payment. It can also serve as proof of income when applying for a loan, renting accommodation or completing certain financial formalities.
Every employee should develop the habit of checking their payslip rather than looking only at the amount credited to their bank account.
Understanding CTC, Gross Salary and Take-Home Salary
These three terms are among the most confusing parts of a first salary structure.
Although they are related, they do not mean the same thing.
Cost to Company (CTC)
CTC is the total annual cost an employer incurs for employing an individual.
It may include:
- Basic salary.
- House Rent Allowance (HRA).
- Other allowances.
- Employer’s PF contribution.
- Employer’s ESI contribution, where applicable.
- Gratuity provisions.
- Bonuses or other benefits included in the package.
For example, if a company offers a package of ₹2,40,000 per year, the monthly CTC equivalent is ₹20,000.
However, this does not necessarily mean the employee will receive ₹20,000 every month.
Gross Salary
Gross salary is the total monthly earnings before employee-side deductions.
It generally includes basic salary and applicable allowances.
For example:
Basic Salary: ₹10,000
Other Allowances: ₹7,000
Gross Salary: ₹17,000
Take-Home Salary (Net Salary)
Take-home salary is the amount actually credited to the employee’s bank account after applicable deductions.
These may include employee PF, ESI, professional tax, TDS and other authorised deductions.
Remember: CTC is the employer’s overall cost, gross salary is your earnings before deductions, and take-home salary is what you receive in your bank account.
Common Components of a Salary Slip
Your salary structure may contain several components depending on the employer, industry and employment agreement.
| Salary Component | Meaning |
|---|---|
| Basic Salary | Fixed core component of salary |
| HRA | Allowance towards house rent |
| Conveyance Allowance | Amount provided for travel or commuting, depending on the salary structure |
| Special Allowance | Additional salary component defined by the employer |
| Incentives | Additional earnings based on performance or targets |
| Overtime | Payment for eligible additional working hours |
| Bonus | Additional payment under applicable company policy or law |
Not every employee receives all these components. Some frontline jobs may have simpler salary structures, while others may include shift allowances, attendance incentives or performance-based payments.
Always check your appointment letter and salary structure to understand what applies to your role.
What Is Provident Fund (PF)?
It is administered through the Employees’ Provident Fund Organisation (EPFO).
In covered employment, contributions are generally made by both the employee and the employer.
How does PF work?
Under the commonly applicable EPF contribution structure:
- Employee contribution: Generally 12% of applicable PF wages.
- Employer contribution: Generally 12% of applicable PF wages.
The employer’s contribution is divided between the Employees’ Provident Fund (EPF) and the Employees’ Pension Scheme (EPS), subject to applicable rules.
The PF wage calculation is not necessarily based on the employee’s entire gross salary. It depends on the applicable wage components and statutory provisions.
Why is PF important?
Long-term savings: Regular contributions help employees accumulate savings over their working years.
Retirement security: The accumulated EPF balance can support financial needs after retirement, subject to withdrawal rules.
Pension benefits: Eligible employees may receive pension benefits under EPS.
Insurance protection: The linked Employees’ Deposit Linked Insurance (EDLI) scheme provides life insurance benefits subject to its conditions.
For freshers, PF may initially look like a reduction in monthly salary. However, it is also a way of building long-term financial security.
What Is Employee State Insurance (ESI)?
It provides medical and certain cash benefits to eligible employees and their families.
Under the commonly applicable contribution rates:
- Employee contribution: 0.75% of wages.
- Employer contribution: 3.25% of wages.
ESI generally applies to eligible employees working in covered establishments, subject to the applicable wage ceiling and coverage rules. The commonly prescribed wage ceiling has been ₹21,000 per month, with a higher ceiling for eligible persons with disabilities.
What benefits does ESI provide?
Eligible insured employees and their families may receive:
- Medical treatment and healthcare services.
- Sickness benefits, subject to eligibility.
- Maternity benefits.
- Disablement benefits.
- Dependants’ benefits in qualifying cases.
- Other prescribed cash benefits.
For someone starting their first job, ESI can provide important medical and social security support.
Example: If an eligible employee has ESI wages of ₹18,000 per month, the employee-side contribution at 0.75% would be ₹135.
The employer’s contribution is separate and should not be confused with the employee’s deduction.
Other Common Salary Deductions
PF and ESI are not the only deductions that may appear on a payslip.
Here are some other common examples.
Professional Tax
Professional tax is a state-level tax imposed on certain salaried employees and professionals.
The amount and applicability vary depending on the state. Not every state imposes it.
Tax Deducted at Source (TDS)
TDS is income tax deducted by the employer from salary based on the employee’s estimated annual tax liability and applicable tax rules.
The amount depends on factors such as:
- Annual taxable income.
- Applicable tax regime.
- Eligible deductions and exemptions.
- Employee tax declarations and relevant information.
Freshers should understand that TDS is not a fixed deduction for everyone. Some employees may have no salary TDS depending on their income and tax position.
Other Authorised Deductions
Depending on the employment agreement and applicable rules, a payslip may also show:
- Salary advances or loan recoveries.
- Employee welfare contributions.
- Insurance premiums.
- Other authorised deductions.
If you do not understand a deduction, ask the HR or payroll team for an explanation.
Understanding Employee Benefits
Your salary is not the only part of your employment package. Some benefits provide financial protection, healthcare support and additional security.
Common employee benefits include:
Provident Fund: Helps employees build long-term retirement savings.
ESI: Provides medical and cash benefits to eligible insured employees and their families.
Gratuity: A statutory terminal benefit payable to eligible employees under applicable conditions, generally linked to qualifying continuous service.
Paid Leave: Employees may receive earned leave, casual leave, sick leave or other leave according to applicable law and company policy.
Maternity Benefits: Eligible women employees may receive maternity-related benefits under applicable legislation.
Bonus: Employees may be eligible for statutory or performance-related bonuses depending on the applicable rules and company policy.
Insurance: Some employers provide group medical, personal accident or life insurance coverage.
Not every benefit is applicable to every employee. Eligibility depends on the relevant law, establishment, employment terms and company policy.
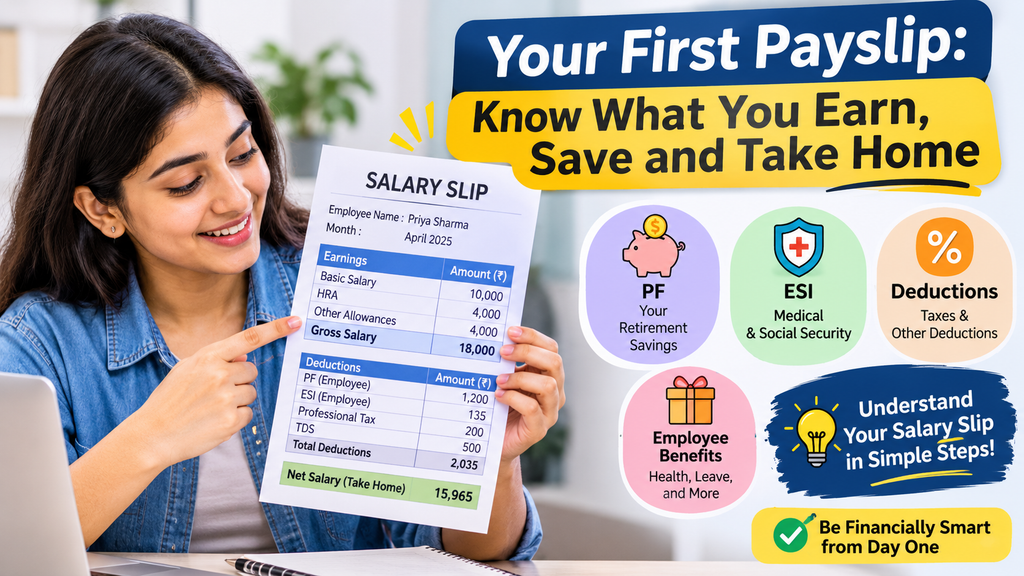
An Illustrative Salary Slip for Freshers
Let’s understand how the different components can appear in a monthly salary slip.
The following is a simplified example for explanation only. It is not a standard salary structure or a statutory calculation for every employee.
Example Employee:
Monthly Gross Salary: ₹18,000
| Earnings | Amount |
|---|---|
| Basic Salary | ₹10,000 |
| HRA | ₹4,000 |
| Other Allowances | ₹4,000 |
| Gross Earnings | ₹18,000 |
| Deductions | Amount |
|---|---|
| Employee PF (illustrative 12% of ₹10,000 PF wages) | ₹1,200 |
| Employee ESI (0.75% of ₹18,000, if eligible) | ₹135 |
| Total Deductions | ₹1,335 |
This example excludes professional tax, TDS, unpaid leave adjustments and other possible deductions. The actual salary will depend on the employee’s salary structure and statutory eligibility.
What Should You Check in Your First Payslip?
When you receive your first payslip, take a few minutes to review the details.
- Check whether your name and employee details are correct.
- Verify the salary period.
- Compare your gross salary with your appointment letter.
- Check whether the attendance and payable days are correct.
- Understand the PF and ESI deductions, if applicable.
- Check any professional tax or TDS deduction.
- Verify the final net salary against your bank credit.
- Ask HR about any deduction you do not recognise.
- Keep a copy of your payslip for future reference.
If you notice an error, raise it with the payroll or HR team promptly rather than ignoring it.
Common Mistakes Freshers Should Avoid
Many first-time employees make avoidable mistakes because they are unfamiliar with salary structures.
Mistake 1: Assuming CTC is the take-home salary.
The CTC includes components that may not be paid directly into your bank account each month.
Mistake 2: Ignoring the salary slip.
Your payslip is an important employment and financial document. Review it every month.
Mistake 3: Not understanding PF and ESI.
These deductions are connected to social security and employee benefits. Understand why they are being deducted.
Mistake 4: Comparing salaries only by the monthly amount.
Two jobs offering the same gross salary may have different allowances, deductions, benefits and working conditions.
Mistake 5: Not asking questions.
If a salary component or deduction is unclear, asking HR or payroll is better than making assumptions.
Conclusion
Your first payslip is more than a record of your monthly salary. It explains your earnings, deductions and the benefits connected to your employment.
Understanding CTC, gross salary, take-home pay, PF, ESI and other deductions helps you make better financial decisions and become more confident in your professional life.
As you begin your career, make it a habit to read your payslip carefully, maintain your salary records and understand your employment benefits.
Your first salary is an achievement. Understanding how it works is the first step towards managing your money wisely.